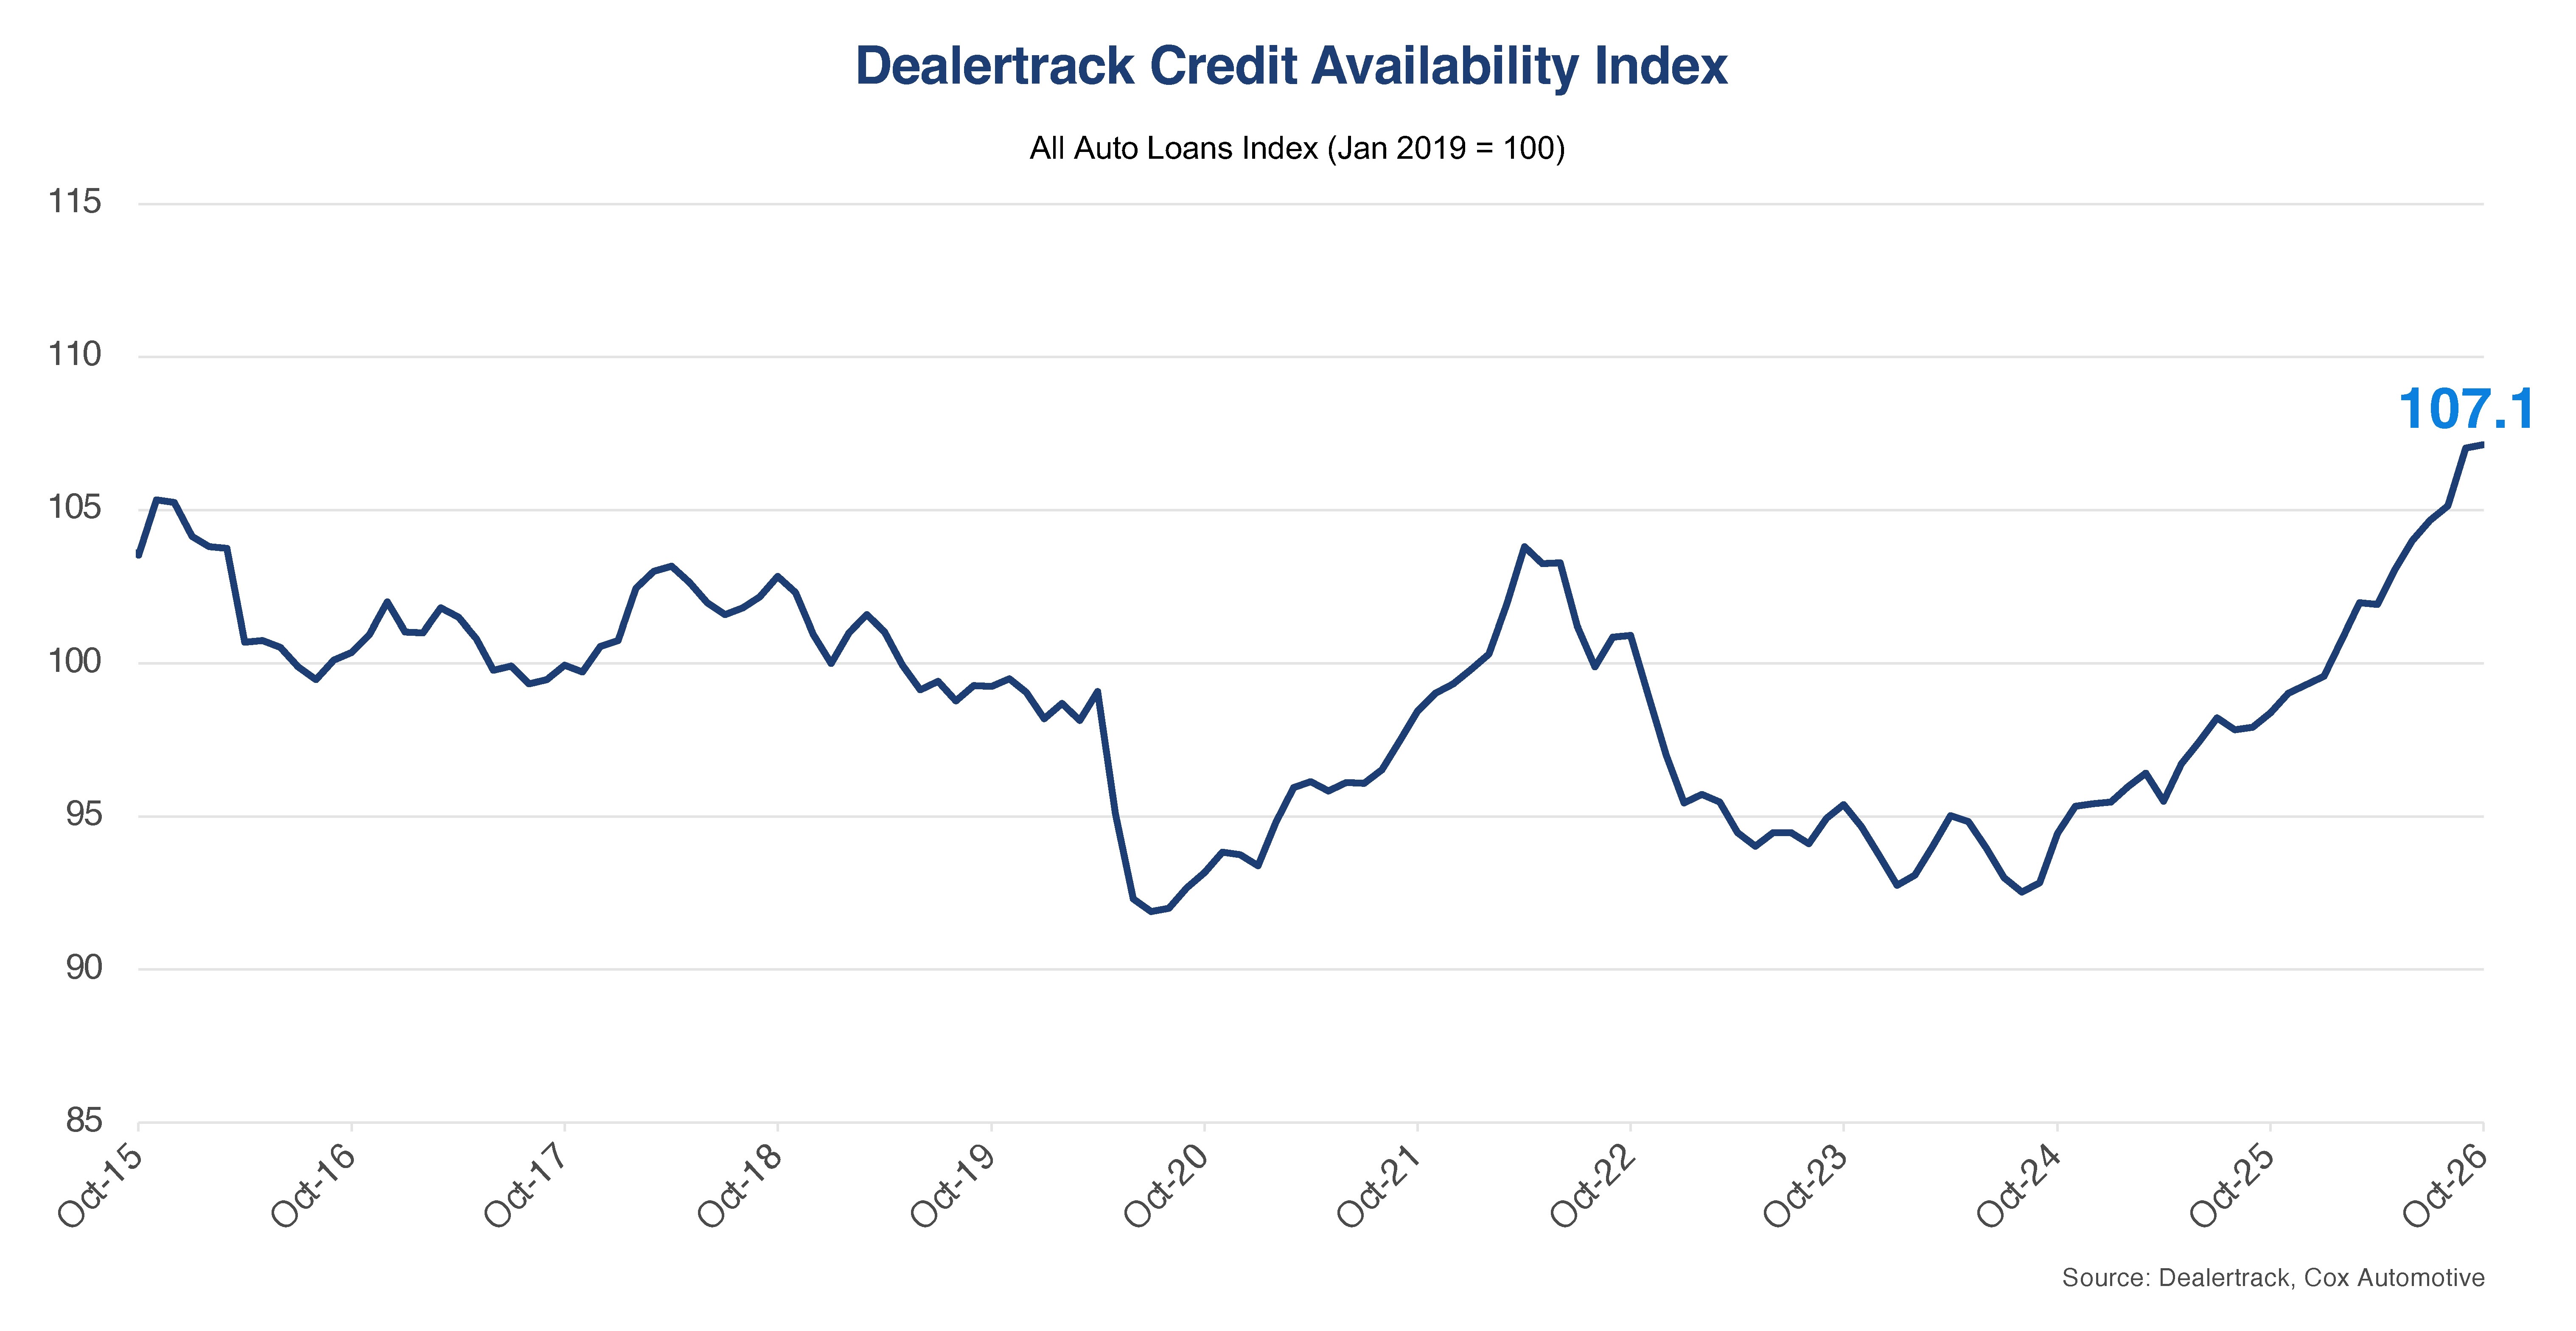
Auto credit access improved for a sixth consecutive month in October, reaching its highest level since April 2015, according to the Dealertrack Credit Availability Index. The All-Loans Index increased 0.1% to 107.1 from a revised 107 in September and was 8.9% higher than in October 2025.
The gain was the smallest of the six-month streak, and the results underneath were much more mixed than in September, when every component contributed. Three components added to the index while three offset most of those increases. A higher subprime share was the largest contributor, while a lower share of long-term loans and a wider yield spread were the biggest drags on the October index.
Key Metrics
- Approval Rates: The overall loan approval rate rose 20 basis points to 73.9% in October and was 240 basis points above the 71.5% recorded a year ago. The increase came despite lower approval rates in most channels and lender types and largely reflected the exit of a near-prime lender whose low approval rate had previously weighed on the overall average.
- Subprime Share: The share of loans to subprime borrowers rose to 17.9% in October, an increase of 50 basis points from September and the third consecutive increase. The increase was broad, with higher subprime shares across all four lender types and every channel. Year over year, the share was up 180 basis points from 16.1%. The rise was the single largest contributor to October’s index gain.
- Yield Spread: The yield spread widened 11 basis points, from 6.42% to 6.53%. The average contract rate rose 24 basis points to 11.46%, its highest level since March 2026, while the 5-year Treasury yield rose 13 basis points to 4.93%, its highest level since June 2007. Contract rates rose across all lender types and channels. Year over year, the spread was 102 basis points below the 7.55% recorded in October 2025. The widening of the yield spread was one of the two largest drags on the October index.
- Loan Term Length: The share of loans with terms longer than 72 months fell to 31.1% in October, down 70 basis points from September’s record high and the first monthly decline since March. The decline was broad, with the share falling in most channels and lender types. It was the fifth consecutive month at or above 31%. Year over year, the share was up 340 basis points from 27.7% in October 2025. The decline in the share of loans with terms longer than 72 months was another factor that weighed on the index.
- Negative Equity Share: The share of loans with negative equity rose to 58.7%, an increase of 90 basis points and the third consecutive increase. It was the highest reading since March’s 59.2%. The increase was concentrated in the used channels. Negative equity was 490 basis points above the 53.8% recorded a year ago and above every monthly reading recorded from 2015 through 2019.
- Down Payment Percentage: Down payments rose to 13.0% in October, up 20 basis points from September’s 12.8%. The increase was broad, with higher down payments across all channels and most lender types. The share was 30 basis points below the 13.3% recorded in October 2025.
Channel and Lender Trends
- Channels: Credit access was mixed across channels in October. Certified pre-owned posted the largest monthly gain, up 1.3% to its best reading since October 2022, followed by All Used, up 0.2%. Non-Captive New declined 0.5%, All New declined 0.3%, and Franchised Used and Independent Used each slipped 0.1%. All Used set a new series high.
- Lender Types: Captives posted the largest monthly gain, rising 2.4% to a new series high, followed by Credit Unions, up 0.4% to their best reading since October 2022. Banks slipped 0.1%, and Finance Companies declined 1%.
Year-Over-Year Comparison
- Channels: All New posted the largest year-over-year gain, up 9.1%, followed by Independent Used, up 8.1%. All Used improved 7.8%, Franchised Used rose 6.2%, and Certified Pre-Owned increased 5.6%. Non-Captive New posted the smallest year-over-year gain, up 4.8%.
- Lender Types: Captives led the year-over-year improvement, up 20.3%, followed by Banks, up 10.5%. Credit Unions improved 10.2%, and Finance Companies increased 6.3%. All four lender types remained well above year-ago levels.
Implications for Consumers and Lenders
Loan structure continued to carry much of the pressure in October, though the signals were more mixed than in September. Negative equity moved further up, while the share of loans longer than 72 months eased from its record and down payments ticked higher. At the same time, the average contract rate rose to its highest level since March, adding to borrowing costs.
- Consumers: More borrowers carried negative equity into their loans in October, with 58.7% of loans financing more than the vehicle’s value. Although fewer loans exceeded 72 months than in September, the share remained above 31% for a fifth month. These structures can make a purchase easier to fit into a budget up front, but they come with higher total borrowing costs and less flexibility to sell or trade the vehicle later if circumstances change. Higher contract rates in October add to that cost.
- Lenders: The yield spread widened in October because contract rates rose more than the 5-year Treasury yield, reversing September’s pattern. This could indicate that contract rates are beginning to catch up with higher Treasury yields. Lenders continued to take on more risk through a higher subprime share and more negative equity, which raises potential losses if borrowers default. If contract rates keep rising, higher payments could make vehicles harder for borrowers to fit into their budget, which may limit how much further loan structures and credit mix can stretch.
Bottom Line: The October 2026 Dealertrack Credit Availability Index rose for a sixth consecutive month to 107.1, its highest level since April 2015. A higher subprime share, increased negative equity and a higher approval rate drove the gain, while a lower share of loans longer than 72 months and a wider yield spread largely offset it. Negative equity rose to 58.7%, its highest level since March.
View historical Dealertrack Credit Availability Index reports.
The Dealertrack Credit Availability Index tracks six factors that affect auto credit access: loan approval rates, subprime share, yield spreads, loan term length, negative equity and down payments. Reported monthly, the index indicates whether access to auto credit is improving or declining. This typically means that it is cheaper and easier for consumers to obtain a loan or more expensive and harder. The index publication timing is shifting to around the 10th of each month.