Key Metrics
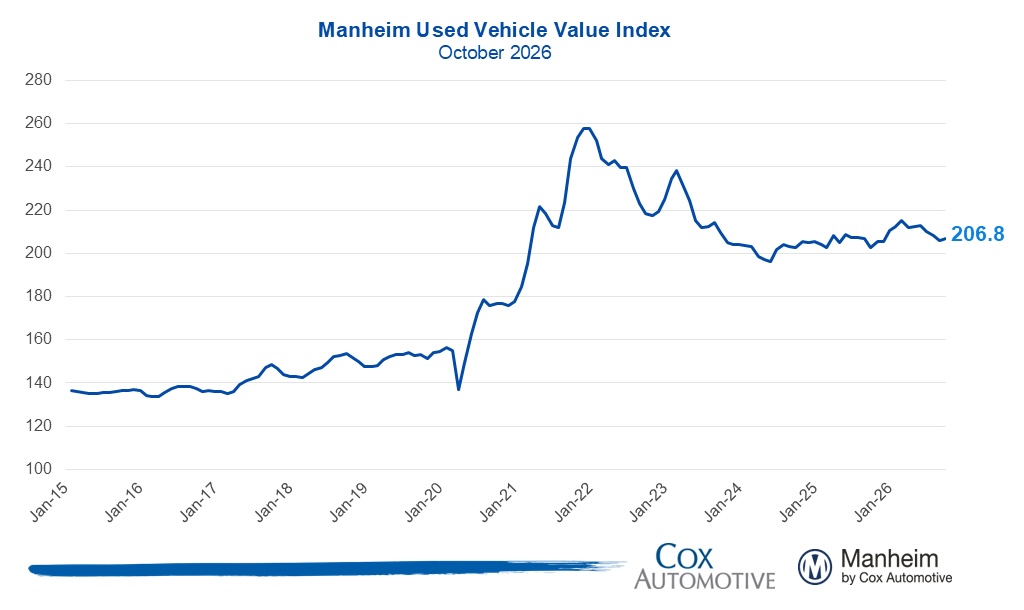
- The Manheim Used Vehicle Value Index (MUVVI) in October was 206.8, reflecting a 2% increase in wholesale used-vehicle prices (adjusted for mix, mileage, and seasonality) compared to October 2025. The Manheim index is up 0.5% month over month. The long-term average monthly move for October is an increase of 0.3%.
- Non-adjusted wholesale vehicle prices are now up 0.3% year over year, but down 2.3% against September. The long-term average monthly move in non-adjusted values for October is a decrease of 1.5%.
Expert Perspective — Jeremy Robb, Chief Economist, Cox Automotive
“Depreciation trends at Manheim were generally in line with long-term averages, with the index holding 2% higher against depressed values last October. This year, we saw less-than-normal depreciation trends in the first half of the year, and then declines accelerated over the summer and early fall. As we got towards the end of October, depreciation slowed a little and was fairly normal from a seasonal point of view.
October is generally the weakest month of the year, and the comparison against last year’s level is noteworthy. In 2025, the EV tax credit ended in September, which made demand stronger for both new and used EVs. When that was over, used EV values fell by 3% in October, and non-EV values fell by over 2%, causing both the index and non-seasonally adjusted values to drop sharply month over month. This year, both categories of vehicles fell on a non-seasonally adjusted basis, but they declined much less than last year.
Gas prices remain elevated and that has helped EV values stay much higher year over year versus non-EVs, even with the increase in off-lease supply. That same trend has also caused light-duty trucks to decline by 4.3% on a non-seasonally adjusted basis year over year, much more than marketwide wholesale prices, which are higher by 0.3%.
As October progressed, we observed used retail inventory holding tighter against last year, with used retail days’ supply currently just under 50 days, almost exactly at the long-term average for the same week of the year. As the days get colder and the nights longer, vehicle sales tend to slow down, but we need to pay close attention to the consumer as we move into the holidays. With the election over, some budding optimism may be brewing, and when you combine that with the oldest car parc in history, solid and steady demand is typically on the horizon.”
Prices, Retention & Sales Conversion
- MMR prices for the Three-Year-Old Index decreased 2.8% in October.
- MMR retention averaged 99%, flat year over year and down 0.3 percentage points from September.
- Sales conversion was 54.2% for the period, 0.1 percentage points lower than the most recent three-year average for October and down 0.2 percentage points from the September rate.
Takeaway: MMR prices for the Three-Year-Old Index decreased by less than the typical 3.1% depreciation for this period. MMR retention decreased less than usual in the month of October. Meanwhile, sales conversion is higher than usual for this time of year.
Segment Performance: Year-Over-Year Price Changes
Overall market prices were up slightly from a year ago, with strength among EVs and Compact Cars partially offset by Luxury, Pickups and SUVs that continue to trend down.
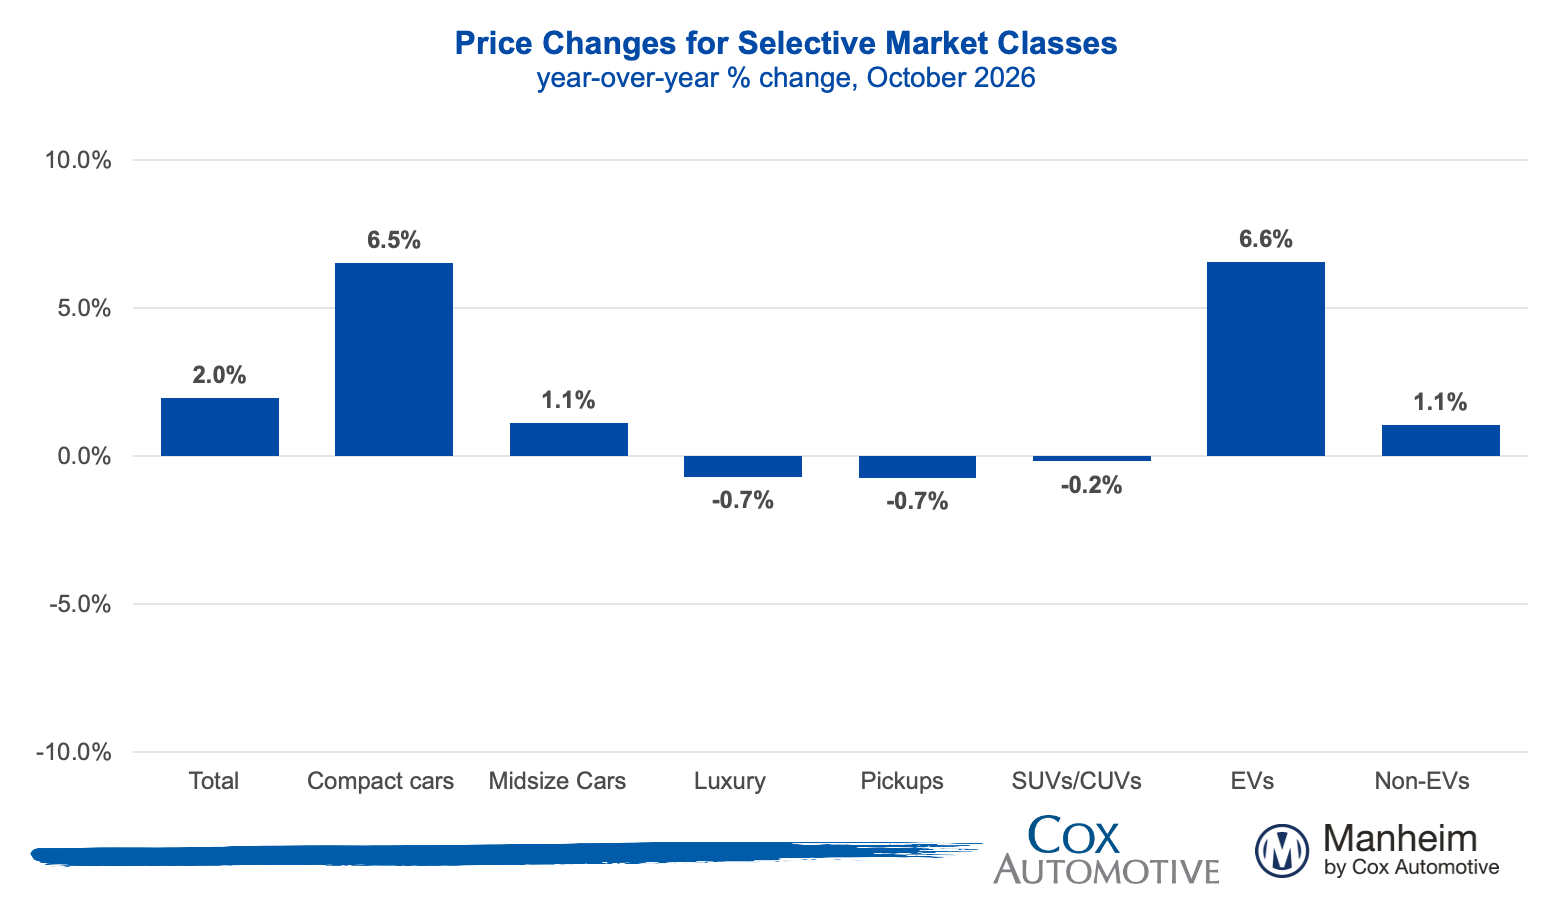
Takeaway: EVs and Compact Cars continue to show relative strength despite values declining over the past two months.
EV versus Non-EV Index
- EVs: The Electric Vehicle (EV) Index was up 6.6% year over year but down 0.9% from September.
- Non-EVs: The Non-EV Index was up 1.1% year over year and up 0.4% from September.
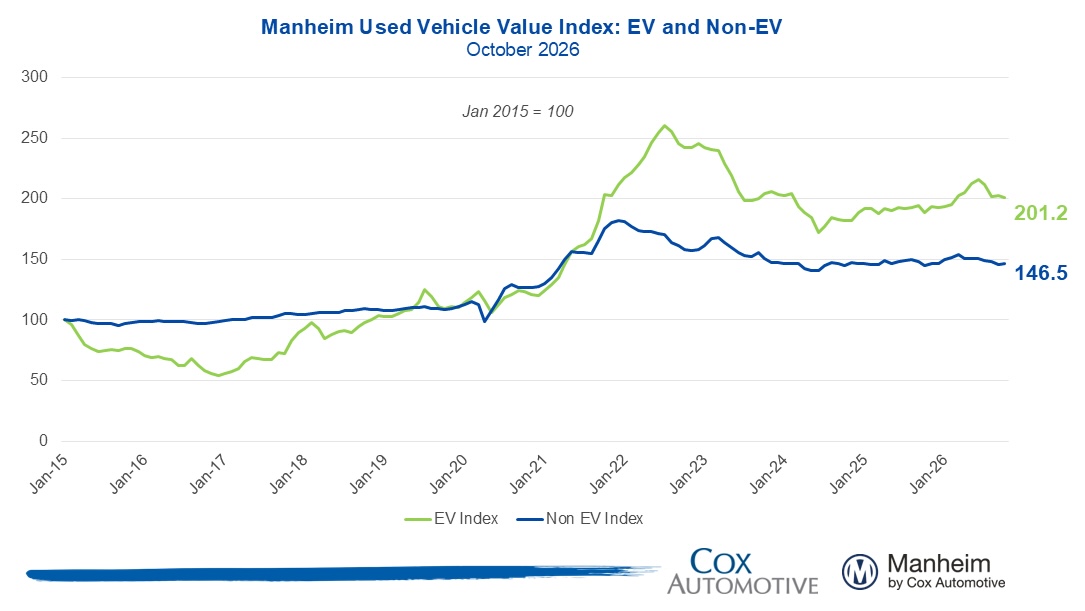
Takeaway: EVs dipped slightly in the past month but remain well above last year, while Non-EVs ticked up from September and are now above year-ago levels.
Wholesale Supply & Rental Prices
- Wholesale supply: At the end of October, wholesale days’ supply was 28.1 days, up 0.1 days year over year but down 0.7 days from September.
- Rental prices: Prices for rental vehicles were 1.9% higher year over year in October, down 1.1% from September. Rental values on a non-seasonally adjusted basis are 1.2% above 2025’s level and decreased 2.9% from September, consistent with lower average mileage, down 14% against last October.
Takeaway: Days’ supply in October was essentially flat against last year and remains within seasonal norms.
View historical MUVVI reports here.
For more information on Manheim: VISIT MANHEIM.COM
The Manheim Used Vehicle Value Index (MUVVI) is a trusted benchmark for tracking wholesale used-vehicle prices in the U.S., which helps dealers and analysts gauge market shifts and anticipate retail trends. The official measure is reported on the fifth business day of each month. The next complete suite of monthly MUVVI data will be released on Dec. 7, 2026.
Cox Automotive has transitioned the quarterly Manheim Used Vehicle Value Index Call from a scheduled live event to a prerecorded, on-demand content release. The Q3 2026 MUVVI Update and its supporting materials are available. See content release.
For questions or to request data, please email manheim.data@coxautoinc.com. If you want updates about the Manheim Used Vehicle Value Index, as well as direct communications on the quarterly updates, sign up for the Cox Automotive newsletter and select Manheim Used Vehicle Value Index quarterly updates.
Note: The Manheim Used Vehicle Value Index was adjusted to improve accuracy and consistency across the data set as of the January 2023 data release. The starting point for the MUVVI was adjusted from January 1995 to January 1997. The index was then recalculated with January 1997 = 100, whereas prior reports had 1995 as the baseline of 100. All monthly and yearly percent changes since January 2015 are identical. Learn more about the decision to rebase the index.